
Long-Term vs Short-Term Rentals South Africa: Which Suits You?

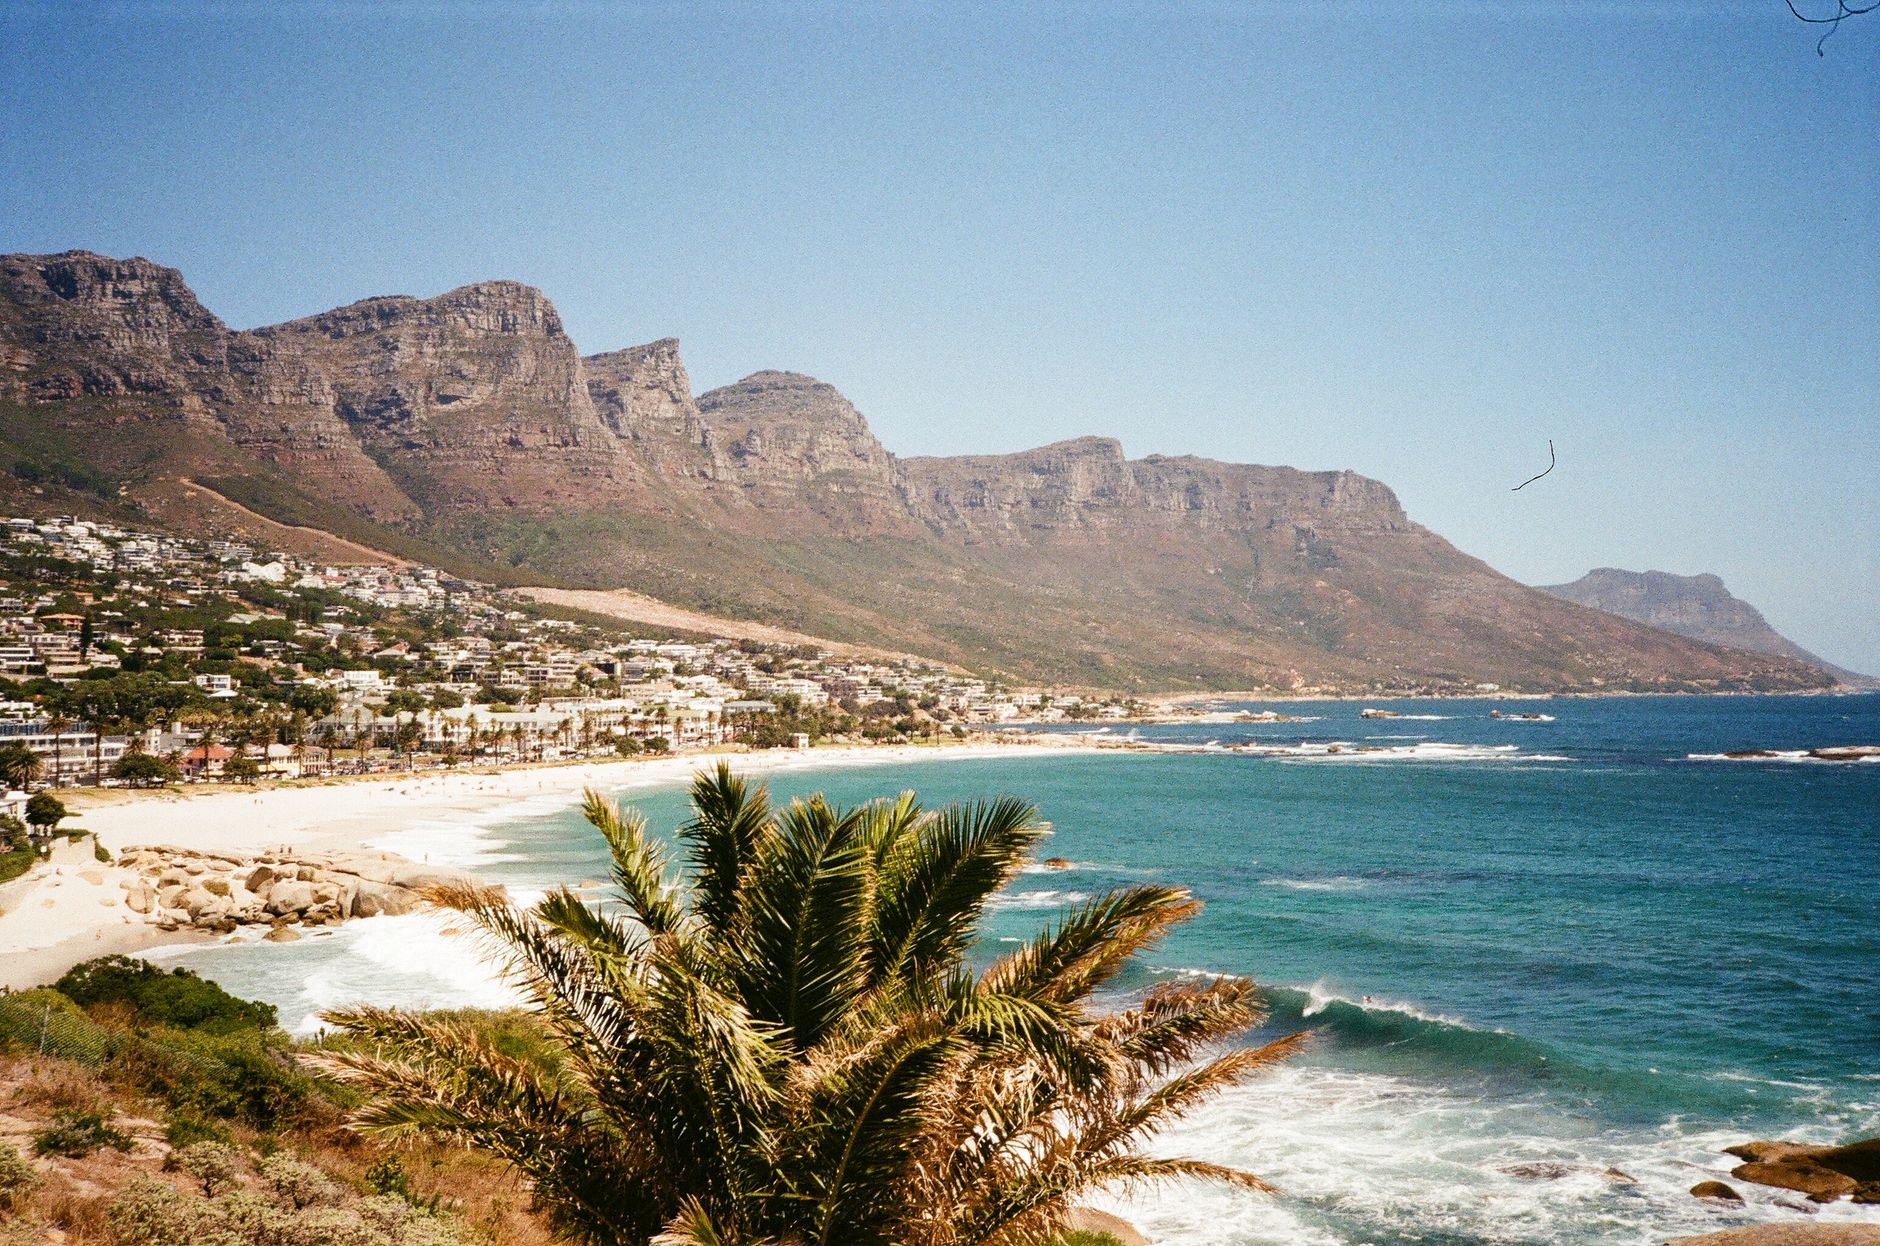
"Which rental strategy fits your portfolio?" Explore the pros and cons of long‑term and holiday rentals in South Africa for informed investors.
Introduction
"Which rental strategy fits your portfolio?" Choosing between long‑term leasing and holiday rental models can change cash flow, tax treatment and management effort. This decision matters in South Africa where local demand, seasonality and regulation vary widely between Cape Town, Johannesburg and coastal holiday nodes.
Market snapshot: long-term vs short-term rentals South Africa
The South African rental market has two distinct faces. Long‑term rentals (12+ month leases) are driven by employment hubs, student demand and affordability. Short‑term or holiday rentals thrive in tourism hotspots — Cape Town suburbs like Sea Point, Camps Bay and Clifton, Garden Route towns, and parts of KwaZulu‑Natal.
Recent market reports (FNB Property, Lightstone, ooba) show that traditional rental yields have softened in major metros due to price recovery and slower wage growth, while holiday rentals recovered strongly after pandemic restrictions eased, especially in Cape Town. However, holiday rental earnings are more seasonal and sensitive to travel trends and municipal regulation.
Financial returns and cash-flow dynamics
Understanding gross yield, net yield and occupancy is essential when comparing strategies.
Long‑term rentals
Pros:
- Stable monthly cash flow and lower vacancy risk once tenants are placed.
- Lower management intensity compared to short‑term rentals.
Cons:
- Lower gross yields in many suburbs (typical gross yields of 4–7%).
- Rent increases limited by market and lease terms.
Example: a Cape Town 1‑bed sectional title apartment bought at R 1,200,000 (~USD 63,000) rented long‑term for R 9,000–R 12,000 (~USD 470–630) per month produces a gross annual yield around 9–12% before costs; net yield after levies, rates, bond repayments and maintenance is typically lower.
Short‑term / holiday rentals
Pros:
- Higher nightly income potential — premium in high season (Dec–Jan, Easter).
- Flexibility to use the property personally or adjust pricing dynamically.
Cons:
- Variable occupancy rates and revenue volatility; marketing and platform fees can be high.
- Increased wear and tear, higher utility and cleaning costs, and stricter municipal rules in some areas.
Example: the same R 1,200,000 (~USD 63,000) apartment in Sea Point could command R 900–R 1,800 (~USD 47–95) per night in peak season. At a conservative 50% annual occupancy at R 1,200 per night, annual revenue is ~R 219,000 (~USD 11,000) before expenses — potentially outperforming long‑term rent but with higher operating costs and vacancy risk.
Costs, taxes and regulation: what investors must budget for
Both strategies share costs (rates, municipal charges, insurance, bond repayments, transfer duty on acquisition) but differ in specifics:
- Levies and sectional title costs: Levies are unavoidable for sectional title units — budget 8–15% of rental income for levies, maintenance and contingency in many complexes.
- Utilities: Often included with short‑term rentals; long‑term tenants usually pay their own utilities except pre‑paid electricity arrangements.
- Taxation: Rental income is taxable under normal income tax rules. Short‑term hosts must correctly declare income and can deduct allowable expenses (marketing, platform fees, cleaning, repairs). Consult SARS and a tax professional for capital allowances and VAT thresholds if you operate at scale.
- Compliance: FICA verification is necessary for property transactions and leases; POPIA affects handling of guest and tenant personal information. Hosts must also ensure compliance with local municipal by‑laws — some areas require registration or business licences for holiday lets.
Short term rental market Cape Town: a special case
Cape Town remains South Africa’s most mature holiday rental market. Demand peaks around summer, international events (e.g., cycling races, sports fixtures) and domestic holiday periods. However, municipal responses to nuisance complaints and housing pressure in certain suburbs have led to stricter enforcement and, in places, registration requirements.
Key considerations for Cape Town investors:
- Location matters: Clifton and Camps Bay can command premium nightly rates (luxury R 10,000+ / night — R 10,000 (~USD 525) and up), but these properties also come with higher purchase prices and council scrutiny.
- Seasonality management: Pricing tools and dynamic minimum‑stay rules help but cannot eliminate off‑season risk.
- Neighbourhood etiquette and homeowner association rules: Many apartment complexes prohibit short‑term letting or require approval; always check sectional title rules and levy meetings.
Operational realities: management, insurance and guest experience
Short‑term letting requires a different operational model: continuous marketing, guest screening, professional cleaning, quick maintenance response, key exchange or smart locks, and hospitality standards. Professional property management firms command 15–30% of gross short‑term revenue but can increase occupancy and protect assets.
Long‑term lets require sound tenant vetting (credit checks, references), a solid lease (OTP can be used as a starting point when purchasing), and regular maintenance. Evictions are governed by the Rental Housing Act and common law — the process can be lengthy and costly if tenant relationships break down.
Risk profile and portfolio fit
Deciding between strategies depends on investor goals, risk tolerance and available time:
- Conservative investor seeking steady income: Long‑term rentals in stable suburbs or near employment centres (Sandton, Rosebank, suburbs around major universities).
- Active investor seeking higher returns and prepared to manage operations: Short‑term rentals in tourism hubs (Cape Town, Knysna, Ballito).
- Diversified portfolio approach: Combine both — hold long‑term properties near job centres while allocating a portion of capital to holiday rental assets for higher upside.
Financing, exit strategy and capital considerations
Banks treat properties differently. Residential bonds are available for buy‑to‑let but most lenders expect the owner to occupy the property unless you have an investment loan or disclose rental intention. LTV ratios and interest rates will depend on borrower profile and property type.
Transfer duty and transactional costs matter: For a R 4,000,000 (~USD 210,000) purchase, transfer duty and conveyancing fees add materially to upfront costs. Consider holding period: short‑term properties in high turnover markets can have higher transactional churn; selling during a downturn can be painful.
Actionable tips and key strategies
- Do the numbers: Build realistic scenarios with occupancy (30–70%), average nightly rate, cleaning and management fees. Use conservative figures for worst‑case planning.
- Know your suburb: Check sectional title rules, levies, and local by‑laws before buying. In Cape Town, confirm registration rules for holiday lets and homeowner association positions.
- Professionalise operations: For short‑term scaling, outsource to a reputable property manager or use a dynamic pricing tool; for long‑term, implement robust tenant screening and a clear lease.
- Tax and compliance first: Register income correctly, keep receipts for deductions, and consult a tax advisor about wear and tear allowances, VAT thresholds and capital gains tax on exit.
- Test the market: Consider starting with a hybrid approach — list as holiday rental during peak months and convert to long‑term in off‑peak periods if allowed by building rules.
How KILICASA helps investors navigate the choice
KILICASA simplifies administrative complexity and improves matching between landlords, tenants and guests. Our platform streamlines documentation (FICA, lease templates, OTP support), connects investors to vetted property managers, and provides local market insights to price strategically. For investors weighing long‑term vs short‑term, KILICASA’s data tools and network reduce time spent on paperwork and improve occupancy through better matching.
Explore listings, manage documents and find trusted partners at kilicasa.co.za.
Conclusion
Choosing between long‑term and short‑term rentals in South Africa depends on your financial goals, appetite for hands‑on management, and the regulatory environment of your chosen suburb. Long‑term rentals offer stability and lower operating demands; short‑term holiday lets offer higher upside but require active management, strong marketing and regulatory due diligence — especially in the short term rental market Cape Town. A blended portfolio often delivers the best of both worlds: steady income from long‑term leases and opportunistic gains from holiday lets. With clear financial modelling, proper compliance and local market knowledge, investors can optimise yield while protecting capital.
KILICASA, because everyone deserves a place.
Frequently Asked Questions
Is short‑term letting legal everywhere in South Africa?
Not universally. Legality depends on municipal by‑laws, sectional title management rules and homeowner association policies. Cape Town and some coastal towns have specific registration and conduct requirements. Always check local regulations and sectional title rules before listing.
Which yields are realistic for an investor?
Long‑term gross yields commonly range 4–7% in metros, while well‑managed short‑term properties in top locations can produce higher gross yields but with greater variability. Always calculate net yields after levies, management fees, taxes and vacancy.
Discover KILICASA, your real estate partner in South Africa
Photo by Marina Zvada on Pexels


